
In this guide, we’ll explore how to navigate balance transfer options in Singapore. Find everything from knowing the best time to consider a balance transfer loan and discovering our top picks for Singapore’s leading balance transfer loans to selecting the right loan for your needs and maximising your balance transfer’s benefits. This will help you make an informed decision and start saving.
The Best Balance Transfer Loans for You

Balance transfers offer a way to consolidate outstanding credit card balances and reduce credit card bills by providing a lower interest rate than the usual credit card interest rate. However, not all balance transfer loans are created equal. Understanding Singapore’s top balance transfer loans will help you make an informed decision.
What Is a Balance Transfer Loan?
A balance transfer loan is a type of credit facility that allows you to transfer outstanding balances from credit cards or other debts onto a new loan with a lower promotional interest rate. Using a balance transfer credit card loan gives you some breathing space to pay off your debt over a specified repayment period, potentially easing your monthly financial burden.
How Does a Balance Transfer Loan Work?
When you take out a balance transfer loan, the lender pays off your existing debt, moving the balance to a new account with a fixed interest rate or, sometimes, a 0% interest rate for a promotional period. You then repay the approved loan amount over a chosen loan tenure.
What Are the Advantages and Disadvantages?
Balance transfers in Singapore offer the benefit of consolidating debts at lower or even 0% interest rates, helping to reduce monthly payments and interest costs in the short term. Below is a quick overview of the advantages and disadvantages of a balance transfer.
| Advantages | Disadvantages |
| Lower balance transfer rates than typical credit card interest rates | Some balance transfers have hidden fees or processing fees |
| A structured repayment period can help in debt repayment | Missing a minimum monthly repayment could incur penalties |
| May come with flexible repayment terms | May require a minimum loan tenure |
| Can help improve credit utilisation ratio by paying off credit card balances | Can impact your credit score if mismanaged |
When To Consider a Balance Transfer Singapore Loan
A balance transfer can be beneficial if you have growing credit card debt due to high-interest charges. Opt for a balance transfer Singapore loan when:
- You’re paying high interest on credit card debts and want to consolidate at a lower rate.
- You have a debt repayment plan within the interest-free or promotional period.
- You’re aiming to improve your financial health and manage debt more effectively.
Best Balance Transfer Loans in Singapore: Our Picks
We’ve gathered a list of Singapore’s top balance transfer loans for 2024, carefully selected based on interest rates, loan terms, and other essential features. Use the table below for a quick comparison. We’ve highlighted the best balance transfer rates to help you make an informed choice effortlessly.
| Best Balance Transfer Singapore Loan Options | Highlights |
| Standard Chartered Credit Card Funds Transfer |
|
| HSBC Personal Line of Credit |
|
| Maybank Fund Transfer |
|
| Citibank Ready Credit Balance Transfer |
|
Standard Chartered Credit Card Funds Transfer
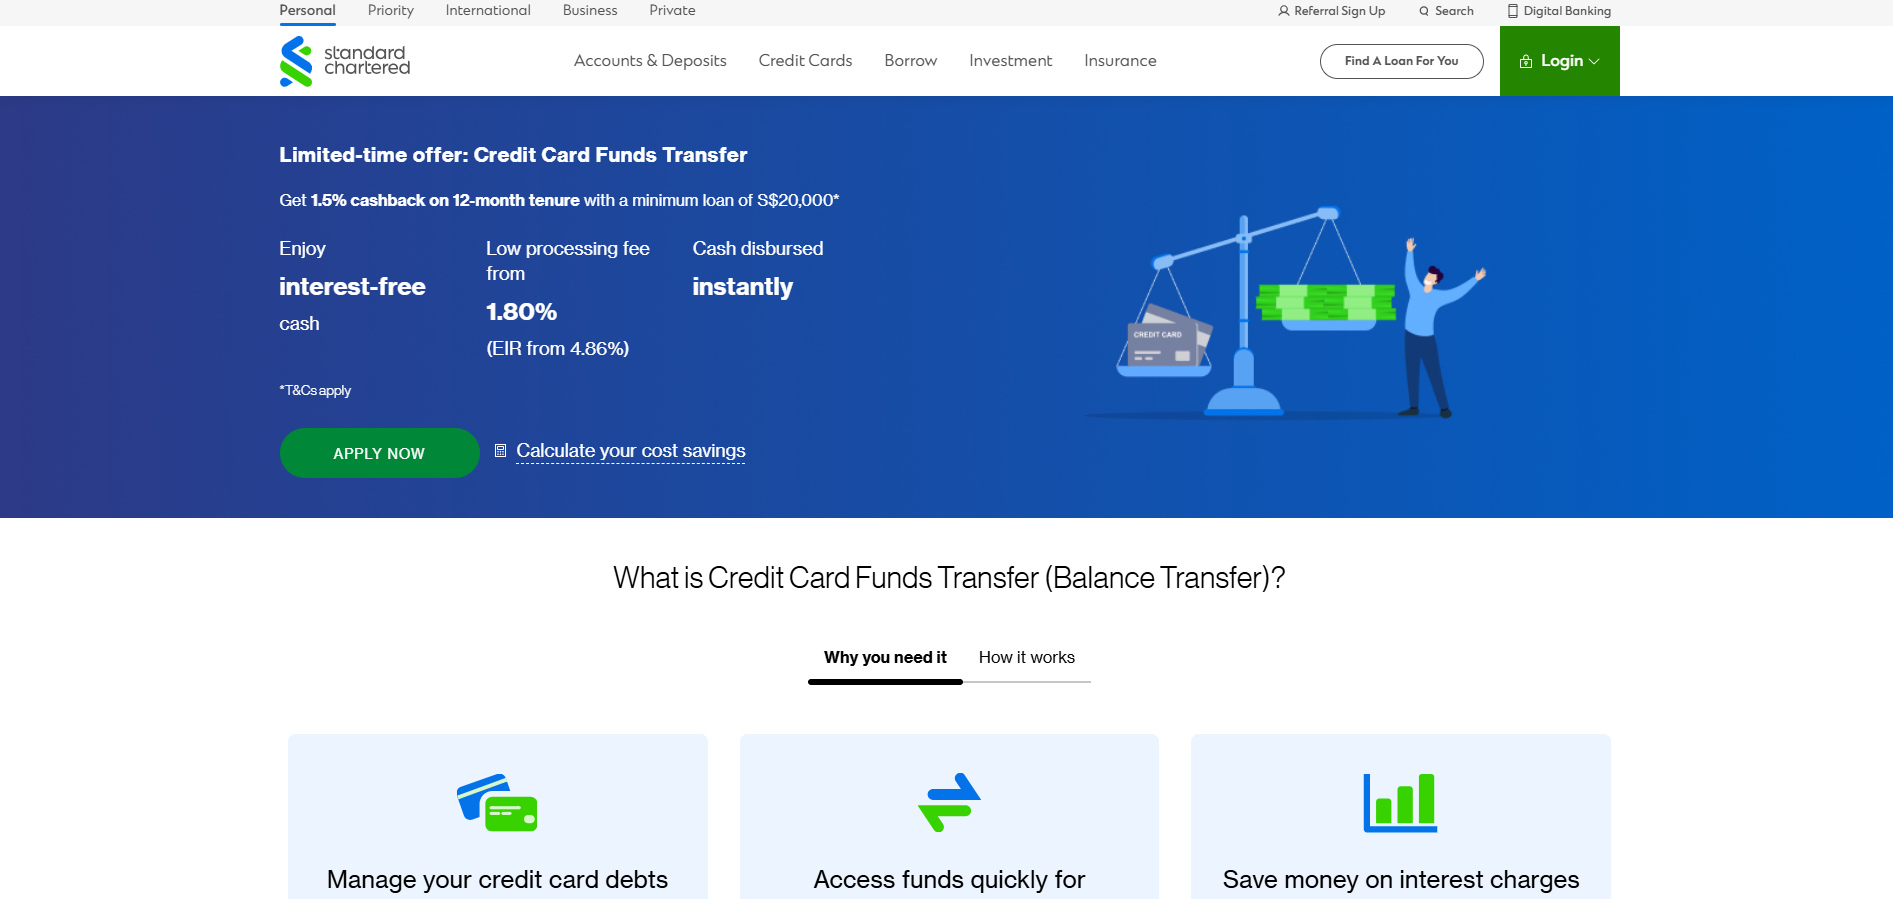
Standard Chartered’s Credit Card Funds Transfer offers a convenient way to manage credit card debts. It offers benefits like 1.5% cashback on a 12-month tenure (minimum loan of S$20,000) and interest-free cash options. With a low processing fee starting at 1.80% (EIR from 4.86%) and fast cash disbursement to any bank account in as little as 15 minutes, this service helps customers consolidate debts at 0% interest.
Eligibility requires a minimum annual income of S$30,000 for Singaporeans and S$60,000 for foreigners, and Standard Chartered cardholders with updated income documents may apply without additional paperwork.
HSBC Personal Line of Credit
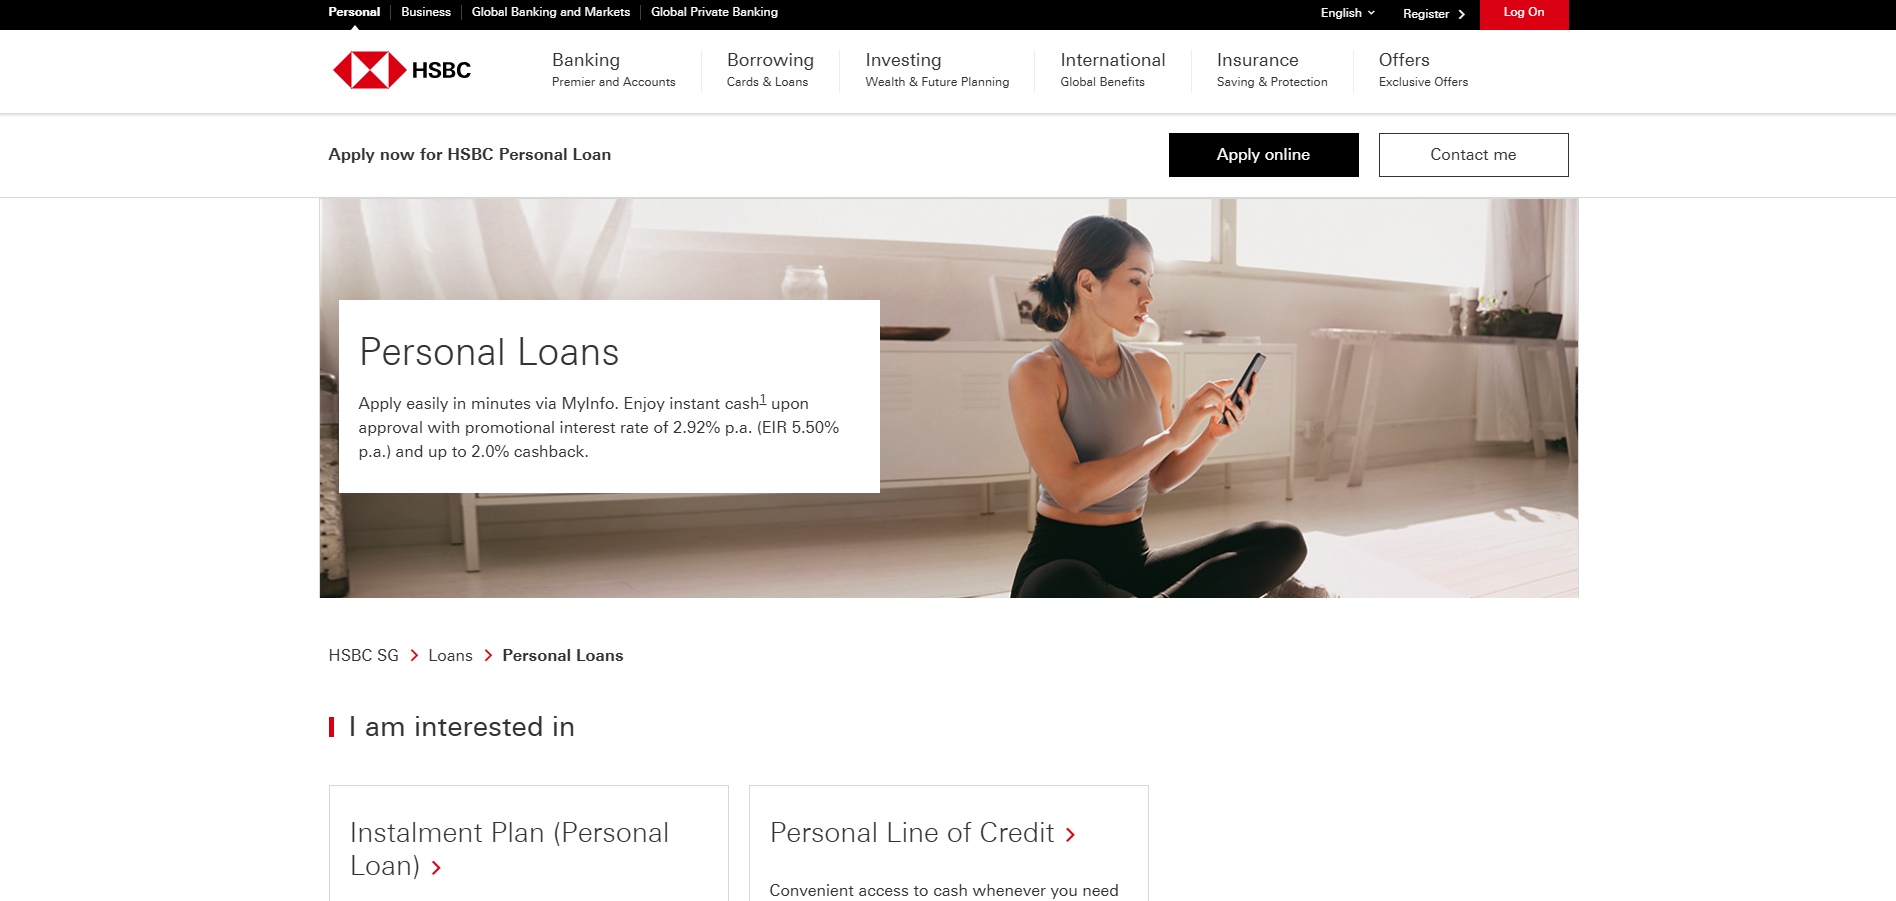
HSBC’s Personal Line of Credit offers flexible financing at competitive rates, ideal for individuals seeking quick access to funds. Eligible Singaporeans, PRs, and foreigners (aged 21-65) with a minimum annual income of S$30,000 for salaried individuals or S$40,000 for self-employed, and foreigners can apply online or via SMS, phone, or Myinfo for a smooth application.
Promotional rates range from 2.92% p.a. (5.50% EIR) to 9.89% p.a. (16.5% EIR), with a 1% processing fee (minimum S$88). HSBC Premier customers enjoy special rates, while interest compounds if not settled monthly. Terms and conditions apply.
Maybank Fund Transfer
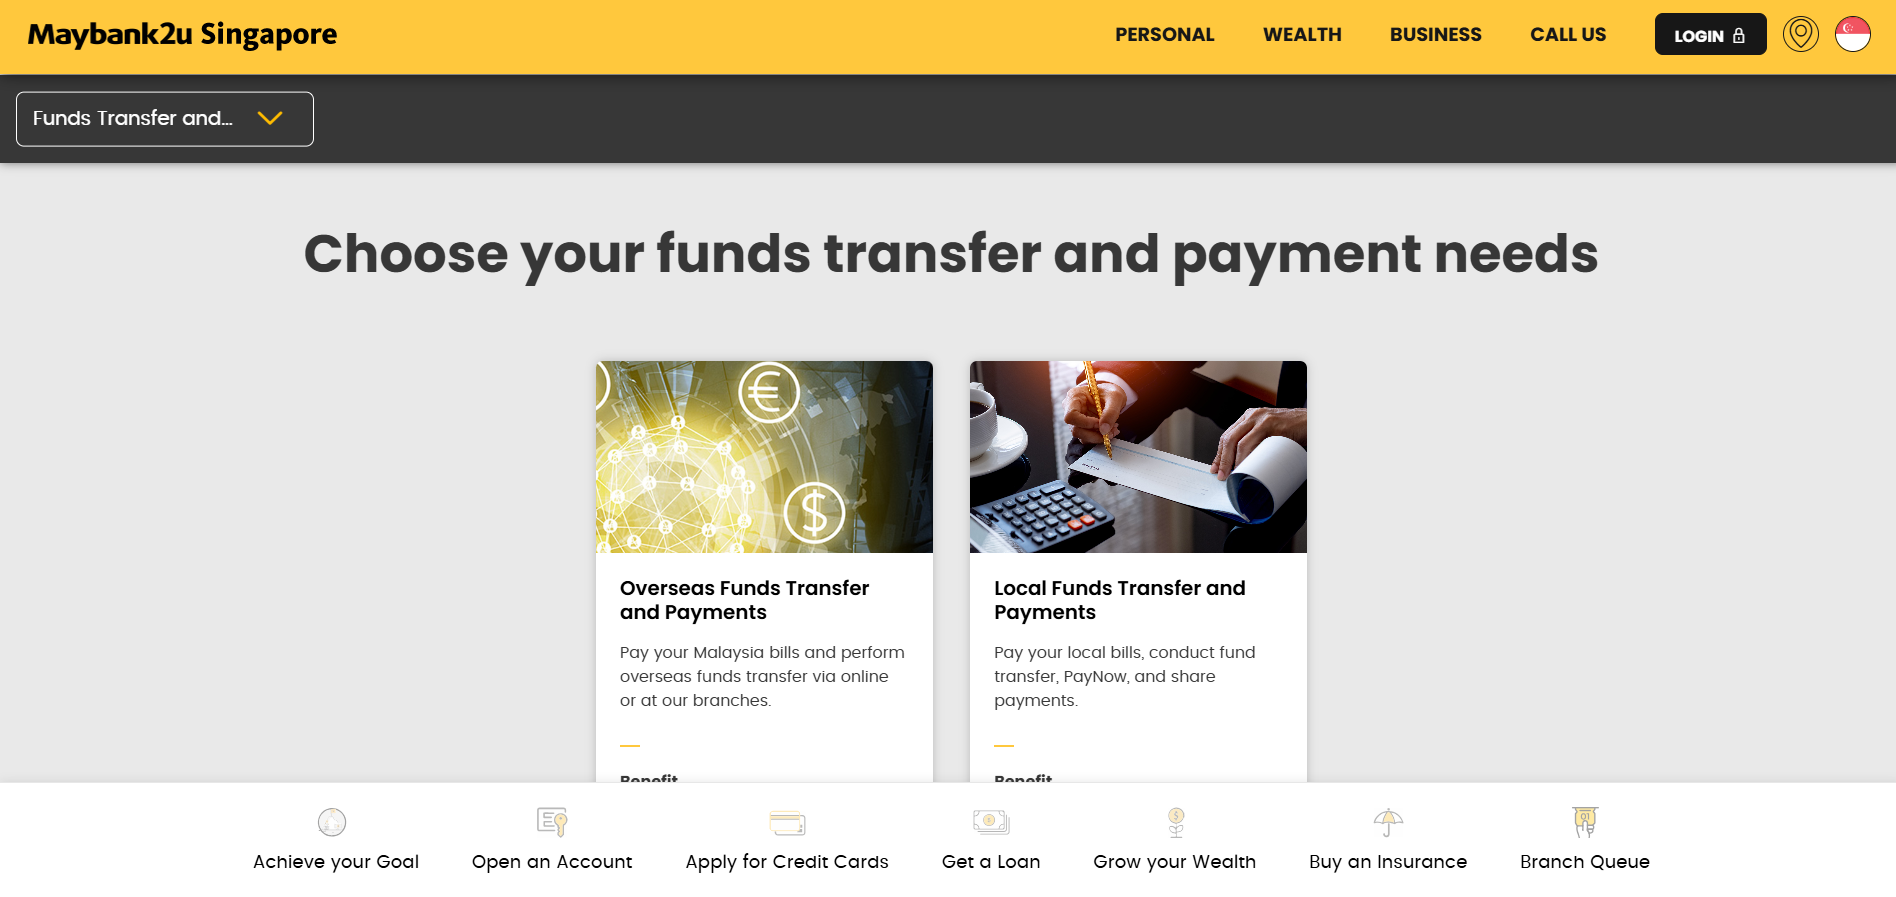
Maybank’s Fund Transfer service provides flexible options for both local and overseas fund transfers with competitive exchange rates and convenient access through online banking or mobile apps. Customers can transfer funds locally using PayNow or Maybank’s QR Scan & Pay.
In contrast, overseas transfers are facilitated via Maybank2u, including instant transfers to the Philippines and affordable telegraphic transfers with a wide range of currencies.
Maybank also offers seamless bill payments in Malaysia, quick local payments through NETS and MEPS, and secure options for electronic payments and shared transactions, providing 24/7 convenience and extensive payment flexibility.
Citibank Ready Credit Balance Transfer

Citibank’s Ready Credit Balance Transfer offers a convenient way to consolidate balances and reduce interest costs. Flexible repayment options are available over 6, 12, or 24 months. Applicants receive a follow-up call from a Citibank officer to assist with completing the application.
With minimum monthly payments that vary based on the current balance, customers can manage their payments efficiently. Payments can start at S$50 or 1% of the outstanding balance and any relevant fees. Note that this offer excludes residents from certain regions and is subject to approval.
Who Can Apply for a Balance Transfer Loan?
Each lender has specific eligibility requirements. Generally, to qualify for a balance transfer application in Singapore, you must:
- Be at least 21 years old
- Meet the minimum annual income criteria, often around S$30,000
- Hold a valid credit card account with the institution
A strong credit profile can also enhance your chances of approval and access to better balance transfer rates.
How To Choose A Balance Transfer Loan
With various balance transfer Singapore options available, understanding the most critical factors can help you choose the best one for your needs.
Interest Rates
Look for competitive interest rates or promotional 0% balance transfer offer rates. Pay attention to whether the rate is fixed or if there’s a promotional interest rate period after which the prevailing interest rate applies.
Processing Fees
Most balance transfers come with an upfront processing fee, which is often lower than ongoing credit card interest but still adds to the total cost of the loan. These fees vary significantly between lenders, so comparing them across options is essential to avoid unexpected costs.
Loan Terms
Choosing the right loan term is important because it needs to match your financial goals and how comfortably you can make repayments. A shorter loan period usually means higher monthly payments, which can be tough for some people. However, it can also help you save money overall by reducing the total interest you pay.
Credit Card Requirements
Certain balance transfer loans are available only to existing credit cardholders or linked to specific credit card balances. Before applying, verify whether you need a particular credit card account to qualify or if the lender requires you to transfer balances from specific banks.
Overall Value
To determine the total value of a balance transfer loan, consider all associated costs, including interest rates, processing fees, and monthly repayments. By assessing the total repayment amount over the loan term, you can judge whether the loan provides genuine savings and meets your financial objectives.
What Is the Application Process for a Balance Transfer Loan?
Applying for a balance transfer loan typically involves the following steps:
- Check Eligibility: Ensure you meet the minimum annual income and credit score requirements.
- Complete the Application: Provide personal details, proof of income, and credit card information.
- Approval and Transfer: Once approved, the lender transfers the approved loan amount to clear your credit card debt.
How To Make the Most of Your Balance Transfer Loan
Using a balance transfer today can be highly effective if managed correctly. To maximise your balance transfer loan:
Prioritise Debt Repayment
Stick to your monthly repayment plan to avoid penalties and keep your balance transfer in good standing. Meeting the minimum monthly repayment is essential, as missing payments could lead to additional fees or a loss of your promotional interest rate.
Avoid Multiple Balance Transfers
Aim to clear your balance transfer within the interest-free period to avoid unexpected interest charges rather than initiating multiple transfers, which could lead to a higher personal loan interest rate. This approach allows you to manage your credit more effectively within your total credit limit.
Plan Repayments Carefully
Avoid making new charges on your credit card while paying down your outstanding balance, as this could increase your debt burden. Calculate your monthly repayment based on your balance transfer loan’s term and interest rates, aligning payments with your financial goals and ensuring they fit within your budget.
Make Sure You Don’t Do This With Your Balance Transfer Loan
Misusing a balance transfer loan can ultimately increase your debt, so it’s essential to avoid these common pitfalls:
Skipping Monthly Payments
Missing a monthly payment impacts your credit score and incurs costly fees, which can add to your financial burden. Staying consistent with payments ensures you reduce your credit card bills rather than adding to them, keeping you on track with your debt reduction goals.
Ignoring Processing Fees and Hidden Costs
Be aware of all fees, including processing fees and any hidden costs, as they can significantly impact the overall cost of your loan. Factoring these fees into your budget helps you avoid unexpected expenses and makes repayment easier.
Overusing Balance Transfers
Applying for multiple balance transfers within a short period can damage your credit score by increasing your credit utilisation ratio. Overuse can also lead to accumulating more debt if not managed carefully, so it’s best to focus on repaying your current balance transfer loan before considering another.
Is a Personal Loan a Good Alternative To Balance Transfers?
If a balance transfer doesn’t suit your needs, a personal loan might be another option. Here’s a comparison of balance transfer loans and personal loans:
| Balance Transfer Loan | Personal Loan |
| Usually, lower interest rates or promotional rates | Higher personal loan interest rate but can cover a larger loan amount |
| Short-term repayment period | Long-term, flexible repayment terms |
| Limited to credit card debt or credit card bills | Can be used for various financial needs |
When To Get a Personal Loan Instead
Getting a Singaporean personal loan may be more suitable if you need to consolidate multiple types of debt beyond credit card balances. Unlike balance transfer options, which often target short-term credit card debt, a personal loan can provide a more comprehensive solution for consolidating debt.
A personal loan is generally advantageous if you require a longer-term repayment plan. With personal loans, you can often choose repayment periods that span several years, offering a more manageable approach for larger debt balances that may need more repayment time.
Conclusion
Finding the best balance transfer in Singapore can ease debt stress, help you save on the bills of your credit card and its interest, and improve your overall financial health. You can significantly impact your financial planning by comparing balance transfer options, considering factors like processing fees, and assessing the loan tenure.
Remember to evaluate how the transfer affects your credit score and to carefully plan your repayment period to stay on track with your financial goals. For more comprehensive insights on managing debt and enhancing your financial well-being, explore the OMY official website. Discover in-depth resources tailored to help you make informed financial decisions in Singapore.


